News
Savings Tax Rises to 24% From April 2027: Budget 2026
The Budget on 28 October raised tax on savings interest again, and then reversed last year’s decision to cut the cash ISA limit, so the ISA has become more valuable twice over in the same week. HMRC published the detail on 29 October. The other item is for anyone who took advice from Verus Financial Services: claims are now open.
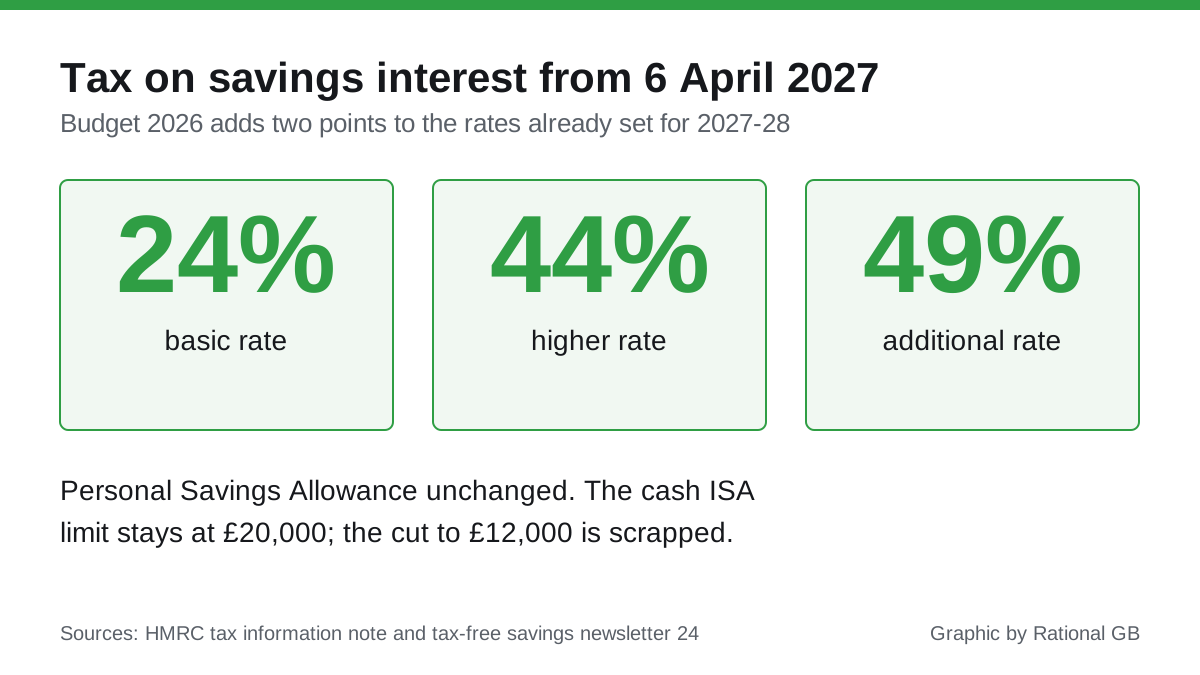
Tax on savings interest rises to 24%, 44% and 49% from April 2027
From 6 April 2027, income tax on savings interest above your allowances will be 24% at the basic rate, 44% at the higher rate and 49% at the additional rate, according to HMRC’s tax information note. Budget 2025 had already set those rates at 22%, 42% and 47% for 2027-28; this adds a further two points, so they will be four points above this tax year’s 20%, 40% and 45%. The same rates apply to rental income from property in England, Wales and Northern Ireland.
The Personal Savings Allowance and the starting rate for savings do not change. HMRC estimates around 12% of taxpayers will pay an average of £113 more in 2027-28. It also says a basic rate taxpayer making full use of the starting rate and the Personal Savings Allowance would need more than £150,000 in savings outside an ISA, earning 4%, before paying any tax on interest, so for most people this bites only on larger balances or higher incomes. Interest inside an ISA stays tax-free, which is the simplest fix; our guides to how ISAs work and cash ISA versus stocks and shares ISA set out the choice.
The cash ISA limit stays at £20,000
The cut in the cash ISA limit to £12,000 from 6 April 2027, announced at Budget 2025, will not happen. HMRC’s tax-free savings newsletter says the £20,000 cash limit will be kept and the regulations that introduced the lower limit, and the rules that went with it, will be revoked. The government says it will instead design, with the industry, a new incentive for people investing in a stocks and shares ISA for the first time. No details yet. Our ISA allowance page covers how the £20,000 can be split.
The same newsletter confirms that from 29 October the Lifetime ISA withdrawal charge is 20%, not 25%, when a first-time buyer uses it on a home costing more than £450,000. Our Lifetime ISA explainer covers the rest of the rules.
Former Verus Financial Services clients can now claim from the FSCS
The FCA said on 29 October that former customers of Verus Financial Services Limited can now check whether they can claim compensation from the Financial Services Compensation Scheme, which has opened the firm to claims. Verus was an independent financial adviser giving investment, pension, mortgage, equity release and insurance advice, and has not been allowed to carry out regulated activity since 2025. Claims go to the FSCS (0800 678 1100). If you already have a complaint with the Financial Ombudsman, it will contact you, and your file can be transferred without you resending evidence. The FCA warns that a claims firm is unlikely to add anything for most clients, and that any unexpected call claiming to be from Verus should be ended.